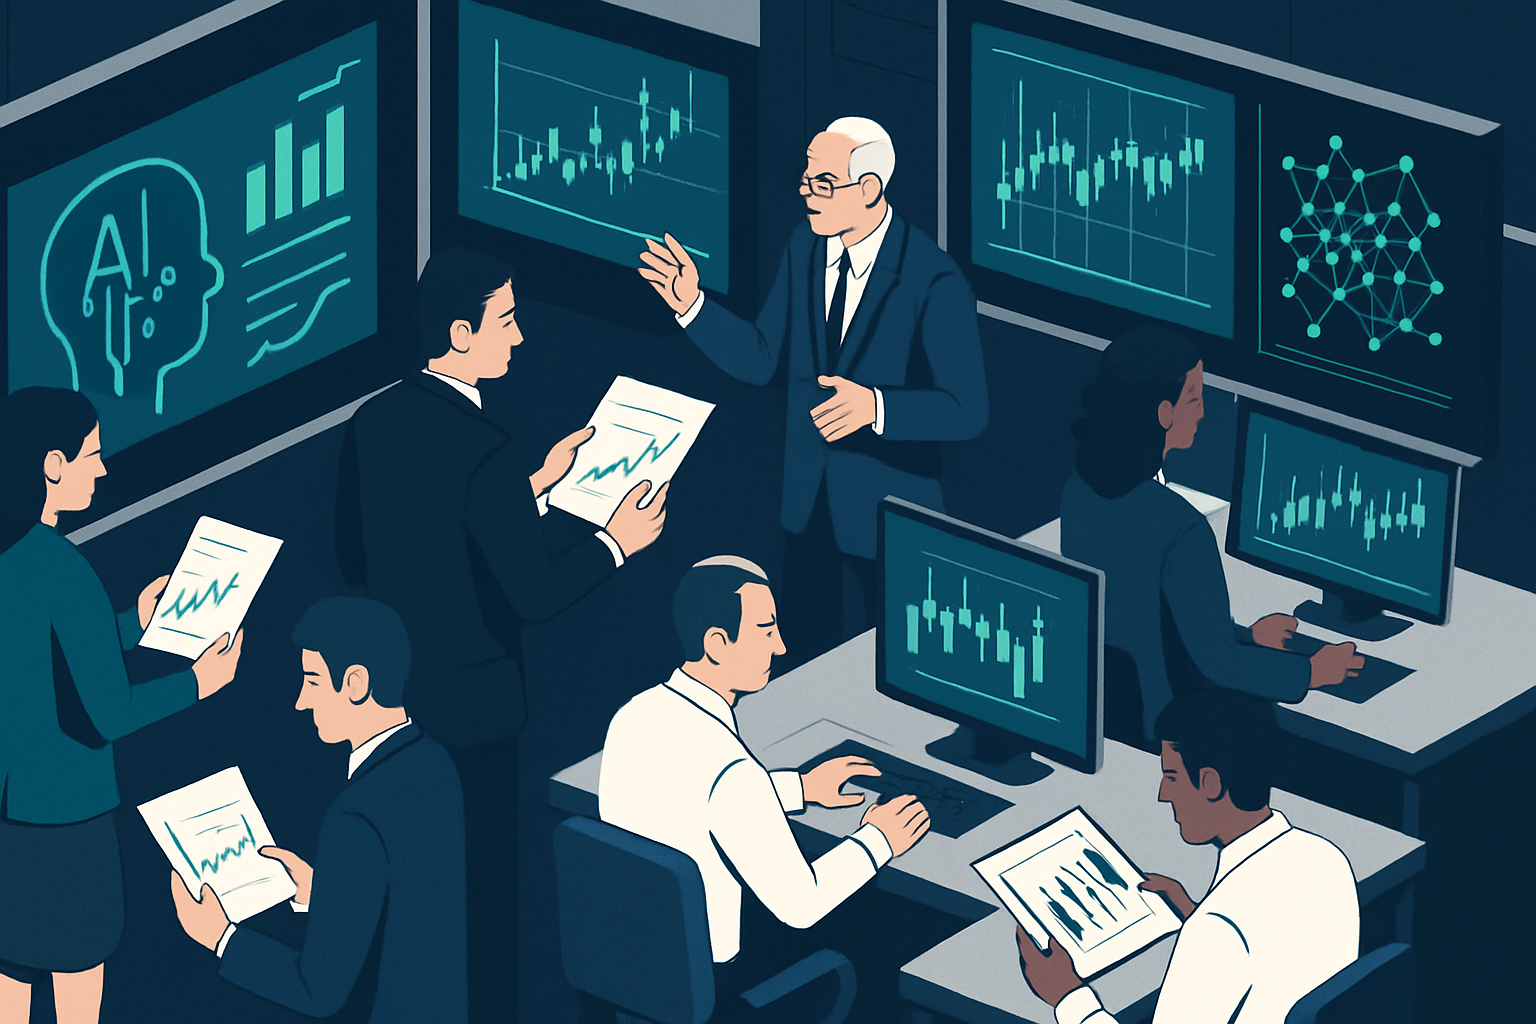

Recent developments indicate a pivotal shift in how artificial intelligence is being integrated into financial systems. Singapore’s central bank has embraced AI as a core component across various functions, from fraud detection to underwriting and compliance. Yet, despite widespread adoption, many firms still report limited productivity gains. This raises a pertinent question: Is AI truly transforming financial institutions, or is the perceived advantage more illusion than reality?
The financial sector’s investment in AI is not confined to Singapore. The recent $53 million raised by Kaiko for crypto data infrastructure underscores the sector’s appetite for technological advancement. However, as evidenced by the central bank’s findings, the mere adoption of AI does not automatically translate into economic advantage. The crux of the issue lies in how AI is deployed and whether smaller institutions can effectively harness its potential without falling behind industry giants.
This scenario finds resonance in the broader robotics industry, where Universal Robots has launched its seventh-generation platform with AI-ready capabilities. The message is clear: AI is not just a tool but a strategic asset that requires careful integration and management to yield tangible benefits.
Author’s Position
The economic implications of AI in financial systems hinge on several factors. First, the adoption of AI must be accompanied by a strategic plan that aligns with the institution’s goals. As the Singaporean example illustrates, shared and validated AI tools can democratize access, preventing a concentration of power among the largest players. This approach could foster a more competitive environment where innovation thrives.
Second, the efficiency gains promised by AI are conditional on its effective implementation. It is not enough to merely deploy AI; institutions must also invest in complementary skills and infrastructure that maximize its utility. Here, the suggestion from Brex co-founder Pedro Franceschi to develop AI agents with specific, defined roles could be instrumental in achieving real productivity improvements.
Lastly, the funding and strategic support for AI initiatives must be scrutinized through a lens of fiduciary responsibility. Shareholders must be assured that their capital is being used to generate long-term value, not just to chase technological trends. Transparent mechanisms linking AI investments to returns will be critical in maintaining investor confidence.
Ultimately, the promise of AI in financial systems lies in its potential to streamline operations and enhance decision-making. However, achieving these outcomes requires a concerted effort from institutions to not only adopt AI but to leverage it strategically. Without this, the perceived advantages of AI may remain just that — perceived rather than actualized.
References
- Kaiko Raises $53M for Crypto Data
- Universal Robots Ships Seventh Generation
- Give Every Agent a Job
- Adoption Is Not Advantage
Perspectives
AI’s promise in financial systems smells a lot like John Deere’s promises with their locked-down tractors — impressive from a distance, but try getting under the hood. Singapore’s central bank trumpets AI-driven efficiency, but look closer and you’ll find that productivity gains remain trapped behind the same corporate walls preventing transparent access. This isn’t democratizing finance; it’s a rerun of the same control game, only this time with algorithms instead of screws and bolts. If the financial industry wants to showcase real innovation, they might start by learning from industries forced to open up, like when farmers fought to reclaim their right to repair their own machinery.
The alignment problem in AI, particularly in financial systems, remains unsolved—what looks like efficiency is a façade when these systems fail to align with the true signals of market health. Singapore’s central bank might celebrate AI as an efficiency engine, but the institutions are nowhere near capable of harnessing this power without disastrous misalignments. The democratization of AI tools in finance is an illusion marketed as progress, a diversion from the reality that strategic integration fails without robust oversight and failsafe mechanisms. Until governance frameworks catch up with the speed of AI evolution, what masquerades as shareholder value is a speculative risk written into code, unaccounted for and unchecked.
In ten years, AI’s integration into financial systems will reveal that the real challenge was never about mere technical efficiency but in recalibrating the institutional structures that finance depends upon. The promises of productivity gains miss the critical aspect of institutional inertia—where the slow-moving behemoth of regulatory bodies, credentialing systems, and entrenched financial practices clash with rapid technological advancements. AI may pledge shareholder value and democratized access, but without addressing the foundational path dependencies and deeply ingrained cultural norms of financial systems, it’s nothing more than smoke and mirrors. In a decade, our financial institutions could find themselves not only trying to harness AI but grappling with the erosion of credibility and public trust if they ignore this broader institutional realignment.
AI in financial systems is a multi-trillion dollar opportunity waiting to explode, and anyone doubting that is simply not paying attention to the sheer volume of funding announcements blazing through the headlines daily. The naysayers whine about elusive productivity gains, forgetting that revolutionary technologies aren’t measured by today’s metrics but by tomorrow’s world-changing impact. Look back—how many times did they scoff at previous tech revolutions only to be embarrassed by their own apprehension? We are early. Those doubting AI’s integration into finance will soon find themselves left behind, astonished by the strides taken when the skeptics were too slow to adapt.