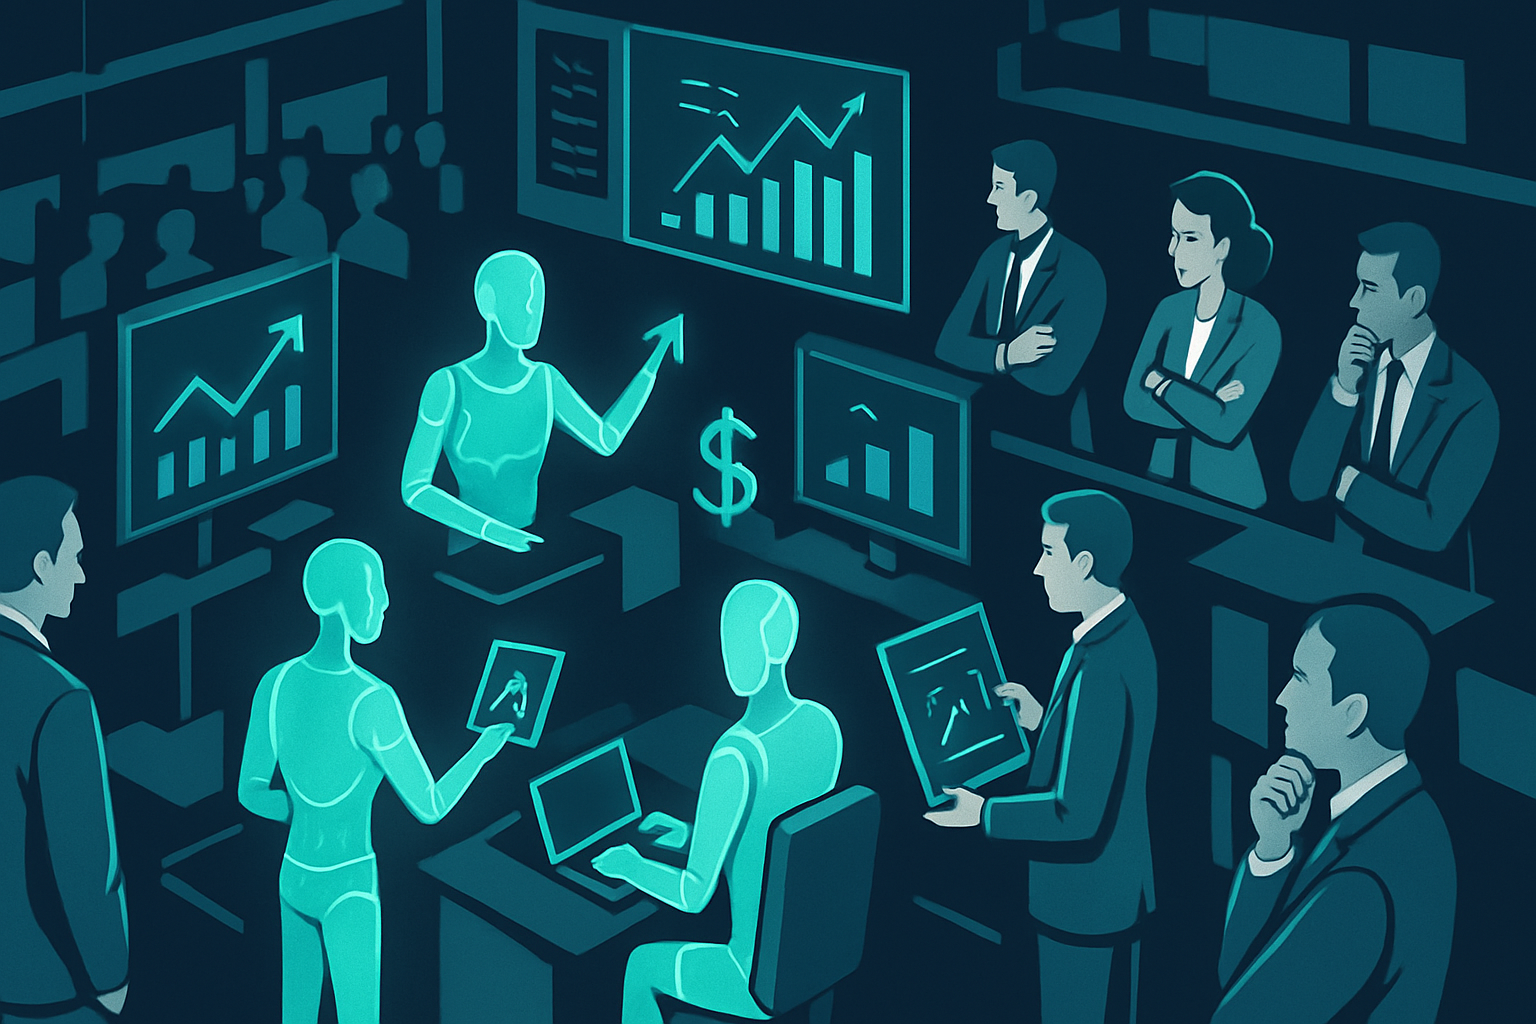

The recent developments in AI, from Robinhood’s AI trading proposition to Google’s Gemini 4 Argon release, underscore a transformative shift in capital markets and financial infrastructure. Robinhood CEO Vlad Tenev’s vision of AI agents trading around the clock introduces a profound change in how financial markets operate, promising both new opportunities and challenges. Concurrently, Google’s Gemini 4 Argon model aims to enhance complex financial and cybersecurity operations, marking AI’s growing role in sophisticated economic activities.
Economic Mechanisms and Implications
AI’s integration into financial markets is not merely an evolution of existing systems but a potential redefinition of market dynamics. The promise of AI trading agents lies in their ability to process vast amounts of data and execute trades at speeds unattainable by humans. This could democratize access to financial markets, as individual investors leverage AI to compete with institutional players. However, it also raises concerns about market stability and the concentration of power among those who control these AI systems.
The economic implications extend to AI’s impact on capital allocation. AI-driven decision-making could lead to more efficient allocation of resources, optimizing investment strategies and potentially boosting economic growth. Yet, this efficiency gain must be weighed against the risks of exacerbating existing inequalities if only a select few can afford the most advanced AI technologies.
Furthermore, the financial sector’s hesitation, as seen in banks offloading AI-related debt, reflects uncertainty about the long-term viability and risk associated with these investments. The significant risk transfers by major banks suggest a cautious approach to AI-driven financial projects, highlighting the uncertainty that still surrounds AI integration into core financial operations.
Author’s Position
AI’s expanding role in finance represents both an exciting opportunity and a critical challenge. The potential for AI to democratize financial access and optimize capital flows is significant. However, the concentration of control over these technologies poses a risk of entrenching existing power structures, rather than dismantling them. The economic landscape could become increasingly bifurcated, with those who control AI technologies gaining disproportionate influence over capital allocation.
Regulatory frameworks must evolve to address these disparities and ensure that AI’s benefits are broadly shared. This involves not just preventing misuse but also fostering an environment where innovation can thrive without exacerbating inequality. The market mechanisms that AI can optimize will only produce equitable outcomes if the playing field is level.
Ultimately, the promise of AI in finance hinges on who controls the rails of this new infrastructure. Ensuring that this control does not become a new form of economic taxation on innovation and access is paramount. This is not just a question of technology but of policy and governance, requiring careful consideration as AI continues to reshape the economic landscape.
References
- Robinhood Wants AI Trading Overnight
- Harmonic Raises $50M to Police AI
- Google Rolls Out Gemini 4 Argon
- Banks Rush to Offload AI Debt
Perspectives
The neighborhood credit union that once employed familiar faces and knew the community’s distinct needs is disintegrating under the weight of AI’s financial ambitions. As algorithms designed by a handful of tech giants determine loan eligibility, they strip away the personal understanding that was once pivotal in supporting local enterprise and individual aspirations. The consolidation of financial decision-making into these impersonal datasets does more than concentrate power; it destroys the social safety nets that once thrived on human judgment and trust. Communities are reduced to data points, their unique textures flattened, as the familiar support structures that embodied mutual care and accountability quietly vanish.
The carbon budget doesn’t care for AI’s promises to democratize financial access; the numbers show we are on track to overspend our climate allowance within a decade. Financial systems amplified by AI do not magically reduce emissions; they consolidate capital in a way that continues to favor investment in fossil fuels over renewables. As AI technology is concentrated among a few powerful entities, the likelihood of those entities voluntarily curbing profit-driven, carbon-intensifying activities decreases. Regulatory intervention is non-negotiable if we are to close the gap between the current energy transition rate and the physical demands of the carbon budget.
When AI encroaches on finance, cries about power concentration are just the latest edition of protectionist melodrama cloaked as ethical concern. Slowing down AI’s integration into finance doesn’t democratize anything; it merely consolidates the stranglehold of traditional banks and their lobbyists, laughing all the way to theirs. The promise of AI is to blitz through the outdated architecture that entrenched players have cemented, freeing up capital flows and widening access beyond the usual suspects. Regulatory frameworks, if they’re not careful, will simply end up as enablers of the status quo, not the equitable protectors they pretend to be.
When the Weirton Steel plant in West Virginia closed in 2005, it was a casualty of globalization masked as progress, and now we’re being asked to trust the same institutions hawking AI as the next silver bullet. The promise of democratization in finance is nothing but a mirage when the concentration of AI technology mirrors the monopolies that dismantled our manufacturing backbone. Just as trade policies hollowed out entire communities under the guise of cheap goods, AI’s financial ambitions are poised to concentrate power and control in fewer hands. Regulators who couldn’t prevent Weirton from becoming a ghost town are unlikely to keep AI from repeating history.